

Germany is often considered an affordable study destination because many public universities charge little or no general tuition for standard degree programs. However, international students still need substantial funds for accommodation, food, health insurance, semester contributions, travel, visa-related expenses, and initial settlement costs.
Private universities, specialized programs, and certain public institutions may also charge tuition fees. Even students joining a tuition-free university may require several lakh rupees to finance a complete degree.
An education loan for Germany can help students pay these expenses without using their family’s entire savings. Indian banks and non-banking financial companies offer secured and unsecured overseas education loans for eligible German universities and courses.
Getting a loan is not only about receiving a sanction letter. Students must understand the interest rate, collateral, margin requirement, co-applicant liability, moratorium, repayment schedule, foreign-exchange risk, disbursement conditions, and German visa requirements.
This guide explains how education loans for Germany work, what they cover, eligibility requirements, required documents, loan application steps, repayment considerations, tax benefits, and common mistakes.
Why Students Need an Education Loan for Germany
The absence of tuition at many public universities does not make studying in Germany cost-free.
Students may need financing for:
Tuition fees, where applicable
Semester contribution
Blocked account
Accommodation
Rental deposit
Health insurance
Food and groceries
Local transportation
Study materials
Laptop and equipment
Visa and residence-related expenses
APS procedure
Language tests
Flight tickets
Initial household purchases
Emergency expenses
The cost varies according to the city, course, university, accommodation type, and length of study.
A student living in a university residence in a smaller city may spend considerably less than someone renting a private apartment in Munich, Berlin, Frankfurt, or Hamburg.
Quick Overview of Education Loans for Germany
| Loan feature | What students should know |
|---|---|
| Available lenders | Public-sector banks, private banks, and education-focused NBFCs |
| Loan types | Secured and unsecured |
| Main borrower | Student |
| Co-applicant | Usually a parent, guardian, spouse, or another lender-approved relative |
| Common expenses covered | Tuition, living costs, travel, insurance, equipment, and eligible academic expenses |
| Interest type | Usually floating, although lender policies differ |
| Moratorium | Commonly course duration plus an additional period |
| Repayment tenure | Can extend for several years, depending on the lender |
| Collateral | May be required for higher loan amounts or weaker profiles |
| Margin money | Borrower contribution may apply |
| Visa use | Loan proof can support the application, but does not automatically replace Germany’s required proof of living funds |
| Tax benefit | Eligible interest may qualify under Section 80E under applicable tax rules |
Every lender applies its own credit, university, course, collateral, and co-applicant criteria.
How Much Education Loan Is Needed for Germany?
The required loan amount should be based on the complete cost of attendance rather than tuition alone.
A student should calculate:
Total loan requirement = tuition + living expenses + semester contributions + insurance + travel + initial settlement costs + academic expenses + emergency reserve − scholarships − personal contribution
Illustrative Two-Year Budget
The following example is only a planning model.
| Expense | Illustrative amount |
|---|---|
| Tuition fees | €0 |
| Living expenses for two years based on the current visa benchmark | €23,808 |
| Semester contributions | €700 |
| Rental deposit | €1,500 |
| Travel | €1,000 |
| Visa, documentation, and initial setup | €1,200 |
| Study materials and equipment | €1,000 |
| Emergency reserve | €2,000 |
| Estimated total | €31,208 |
The rupee amount will depend on the exchange rate used by the lender during sanction and disbursement.
A student attending a tuition-charging university must add the complete tuition amount. Students in expensive cities may also need a larger living-cost estimate than the minimum used for visa purposes.
Current Proof-of-Funds Requirement for Germany
International students must prove that they can support themselves during their studies.
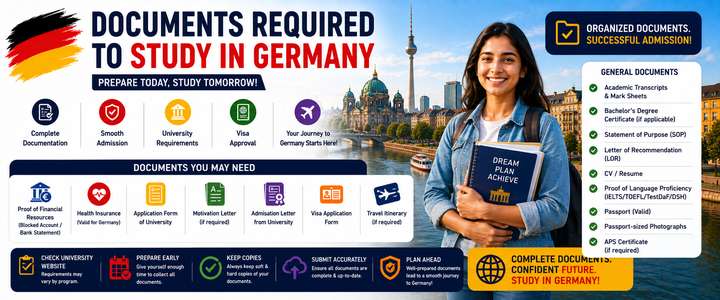
Current guidance from the German Missions in India lists €11,904 for the first year, with a monthly withdrawal limit of €992, when using a blocked account. This amount can change, so students must check the current visa checklist before transferring funds.
Proof of financial resources may generally be shown through an accepted option such as:
Blocked account
Formal Declaration of Commitment from an eligible sponsor in Germany
Qualifying German or European Union scholarship
Other evidence specifically accepted by the responsible German mission
Students who take an education loan should also submit the loan proof requested in the visa checklist.
Does an Education Loan Replace the Blocked Account?
An education loan does not automatically replace the blocked account.
The German Missions in India state that an education loan is additional to the blocked-account requirement. The loan can provide the money used to fund the blocked account, but a loan sanction letter by itself should not be assumed to satisfy the complete proof-of-livelihood requirement.
In practical terms:
The lender sanctions an education loan.
An eligible portion is disbursed for living expenses.
The required amount is transferred to the approved blocked account.
The student submits the blocked-account confirmation and loan documents with the visa application.
Students should not wait until the visa appointment to discover that the sanction letter alone is insufficient.
Types of Education Loans for Germany
Students can generally choose between secured and unsecured education loans.
Secured Education Loan
A secured loan is backed by acceptable collateral.
Collateral may include:
Residential property
Commercial property accepted by the lender
Non-agricultural land
Fixed deposit
Government securities
Insurance policy with an acceptable surrender value
Other financial assets accepted by the lender
Potential advantages include:
Higher loan amount
Lower interest rate
Longer repayment tenure
Better approval chances
Lower pressure on the co-applicant’s income
Greater coverage of tuition and living expenses
Potential disadvantages include:
Property valuation expenses
Legal verification
Longer processing time
Original-document requirements
Risk to the pledged asset if the loan is not repaid
The property owner may need to join the transaction as a guarantor or mortgagor even when that person is not the student’s primary co-applicant.
Unsecured Education Loan
An unsecured education loan does not require property or another pledged asset.
Approval depends more heavily on:
University ranking or lender category
Course
Employment potential
Academic performance
Student’s previous qualifications
Co-applicant income
Credit history
Existing liabilities
Requested loan amount
Destination country
Expected repayment ability
Potential advantages include:
No property mortgage
Faster processing in suitable cases
Fewer legal and valuation procedures
Useful for families without acceptable collateral
Potential disadvantages include:
Higher interest rate
Lower approved amount
Stricter university and course lists
Stronger co-applicant requirements
Shorter repayment tenure in some cases
Higher monthly installment
Greater dependence on projected employability
An unsecured loan is not automatically better simply because no property is pledged. The total repayment cost can be much higher.
Banks vs NBFCs for Germany Education Loans
Indian students can apply through public-sector banks, private banks, or non-banking financial companies.
Public-Sector Banks
Public-sector banks may offer:
Competitive interest rates
Longer repayment periods
Secured overseas education loans
Lower processing charges under selected schemes
Transparent branch-based procedures
Products for full-time study abroad
Possible limitations include:
Longer processing
Detailed documentation
Conservative property valuation
Strict collateral requirements
Multiple branch visits
Less flexibility for unusual academic profiles
Examples of overseas education products include SBI Global Ed-Vantage and Bank of Baroda’s Baroda Scholar scheme. Product names, rates, university lists, and collateral rules can change.
Private Banks
Private banks may provide:
Faster digital processing
Dedicated overseas education teams
Flexible service
Unsecured options for selected universities
Convenient disbursement support
Possible limitations include:
Higher rates for certain profiles
Processing charges
Insurance bundling
Strong co-applicant requirements
Institution-specific lending limits
Education-Focused NBFCs
Education-focused NBFCs may consider applications that traditional banks decline.
They may be more flexible about:
Nontraditional courses
Future earning potential
Unsecured funding
Co-applicant profile
Faster sanctions
University-specific assessment
However, students should carefully examine:
Annual Percentage Rate
Processing fee
Insurance cost
Prepayment conditions
Penal charges
Interest capitalization
Foreign-remittance charges
Repayment tenure
Variable-rate risk
The quickest approval is not necessarily the least expensive loan.
What Expenses Can an Education Loan Cover?
Coverage differs by lender, but an overseas education loan may include:
Academic Expenses
Tuition fees
University registration charges
Examination fees
Laboratory charges
Library charges
Semester contribution
Study tours required by the program
Thesis expenses
Books and study materials
Laptop or computer
Academic equipment
Living and Travel Expenses
Blocked-account funding
Accommodation
Hostel charges
Food and personal living expenses
Health insurance
Travel to Germany
Local travel related to study
Residence-related expenses
Initial settlement costs
Other Eligible Costs
Visa fee
Language test fee
APS-related expenses where allowed
Admission application charges
Caution deposit
Educational insurance
Exchange-program expenses
Mandatory academic visits
Lenders may impose sub-limits on travel, equipment, living costs, or miscellaneous expenses. Students should obtain written confirmation rather than relying on verbal assurances.
Education Loan Eligibility
Eligibility varies, but lenders generally evaluate both the student and co-applicant.
Student Eligibility
Common requirements include:
Indian citizenship or eligible residency status
Admission to a recognized German institution
Admission to an eligible full-time course
Satisfactory academic record
Appropriate previous qualification
Acceptable study gap, if any
Reasonable career progression
Required language proficiency
Ability to meet visa and admission conditions
Course Eligibility
Lenders commonly prefer:
Bachelor’s degrees
Master’s degrees
MBA programs
Engineering and technology programs
Computer science and data-related courses
Natural sciences
Healthcare programs recognized by the lender
Professional degrees
Doctoral programs
Employment-oriented postgraduate courses
Language-only programs, short certificate courses, pathway programs, online courses, and unrecognized institutions may not qualify.
University Eligibility
The lender may classify German universities into categories based on:
Academic reputation
Accreditation
Historical placement outcomes
Course quality
Graduate employability
Previous loan performance
Public or private status
Recognition by relevant authorities
A university’s general reputation does not guarantee that every program will qualify for the same loan amount.
Co-Applicant Eligibility
The co-applicant may be required to provide:
Stable income
Acceptable credit score
Regular banking history
Income-tax returns
Salary slips or business records
Proof of relationship
Limited existing debt
Ability to service interest or installments if required
Parents are commonly accepted as co-applicants. Some lenders may permit a spouse, sibling, guardian, or another close relative under specific conditions.
Secured Loan Collateral Requirements
Collateral acceptance depends on legal title, marketability, valuation, location, and lender policy.
Property Documents Commonly Required
Registered sale deed
Title documents
Previous ownership chain
Property-tax receipts
Approved building plan
Encumbrance certificate
Mutation or municipal records
Occupancy or completion certificate where applicable
Society documents
No-objection certificate where required
Latest utility bills
Identification documents of property owners
Common Collateral Problems
A lender may reject or reduce the value of collateral because of:
Disputed ownership
Incomplete title chain
Unapproved construction
Agricultural land restrictions
Joint ownership without consent
Existing mortgage
Legal notice
Remote or difficult-to-sell location
Low valuation
Missing municipal approval
Property held through an unacceptable arrangement
Families should verify collateral documents before paying nonrefundable loan-processing or university expenses.
Interest Rates on Education Loans for Germany
There is no single education-loan interest rate fixed for all lenders.
The Reserve Bank of India permits scheduled commercial banks to determine education-loan rates according to their approved policies.
A floating interest rate may be calculated as:
Interest rate = benchmark rate + lender spread
The final rate may depend on:
Secured or unsecured loan
Institution category
Course
Loan amount
Co-applicant credit profile
Collateral quality
Repayment tenure
Applicant gender under eligible concession schemes
Relationship with the bank
Internal risk assessment
Students should compare the Annual Percentage Rate, not only the advertised interest rate.
The APR can reflect the annual cost after considering applicable charges included under regulatory disclosure rules.
Fixed vs Floating Interest Rate
Floating Rate
A floating rate changes when the lender’s benchmark or applicable spread changes.
Advantages:
May fall if benchmark rates decrease
Often used for long-term education loans
May provide flexible prepayment terms
Risks:
EMI may increase
Repayment tenure may extend
Total interest is uncertain
Rate changes can affect the budget after graduation
Fixed Rate
A fixed rate is intended to remain constant for the specified period, subject to the loan agreement.
Advantages:
Predictable EMI
Easier long-term planning
Protection from benchmark increases during the fixed period
Risks:
Initial rate may be higher
Fixed period may be limited
Conversion or reset conditions may apply
Prepayment rules may differ
Students should confirm whether a product described as fixed is fixed for the entire tenure or only an initial period.
Understanding the Key Fact Statement
Borrowers should request and review the lender’s Key Fact Statement.
Important entries include:
Sanctioned loan amount
Interest rate
Fixed or floating classification
Benchmark and spread
Annual Percentage Rate
Repayment tenure
Moratorium
EMI
Processing fee
Legal and valuation charges
Insurance premium
Penal charges
Prepayment conditions
Interest-reset frequency
Total repayment estimate
The Reserve Bank of India requires applicable charges and penal-charge information to be disclosed clearly. Students should not sign blank forms or depend only on a salesperson’s verbal explanation.
Processing Fees and Additional Charges
The total cost of a loan can include more than interest.
Possible charges include:
Application fee
Processing fee
Legal opinion fee
Property valuation fee
Mortgage-registration expenses
Stamp duty
Documentation fee
Insurance premium
Credit-report fee
Foreign remittance charge
Currency-conversion markup
Tax on applicable services
Penal charges
Rate-conversion fee
Account-maintenance charge
Ask whether the processing fee is refundable if the loan is rejected, sanctioned for a lower amount, or not disbursed.
Margin Money
Margin money is the portion of the total education cost that the borrower must contribute.
For example, if the eligible cost is ₹30 lakh and the lender applies a 10% margin:
Borrower contribution: ₹3 lakh
Loan contribution: ₹27 lakh
Margin rules may differ based on:
Loan amount
Country
Institution
Secured or unsecured status
Scholarship
Lender product
Expense category
Some lenders require the borrower to contribute the margin proportionately with each disbursement. Others may require proof that the margin has already been paid.
Moratorium Period
The moratorium is the period during which regular EMI repayment is postponed.
A typical education-loan moratorium may include:
Course duration
Additional period after course completion
A shorter period after securing employment, depending on the agreement
A moratorium is not automatically interest-free.
Interest commonly continues to accumulate during the study and moratorium period. If it is not paid, it may be added to the principal before EMI calculation.
Why Moratorium Interest Matters
Suppose a student borrows ₹30 lakh at a floating rate of 9.5%.
If interest is not serviced during a two-year course and an additional moratorium period, the outstanding balance at repayment may be substantially higher than ₹30 lakh.
The exact increase depends on:
Disbursement dates
Whether interest is simple or compounded during the moratorium
Rate changes
Course duration
Moratorium length
Partial interest payments
Lender method
Paying simple interest during study can reduce the later EMI and total repayment, but families should retain an emergency reserve before committing to monthly payments.
EMI and Repayment Example
Assume:
Loan amount: ₹30 lakh
Interest rate: 9.5% per year
Repayment tenure: 10 years
EMI begins immediately on the original principal
The approximate EMI would be around ₹38,800 per month.
This is only an illustration. If accumulated moratorium interest is added to the principal, the EMI will be higher.
When comparing offers, calculate:
EMI
Total interest
Total repayment
Outstanding balance after moratorium
Cost if the rate rises by 1%
Cost if repayment takes five additional years
Savings from paying interest during study
A lower EMI obtained by extending the tenure may produce a much higher total interest cost.
Foreign-Exchange Risk
An Indian education loan is generally sanctioned in rupees, while German expenses are paid in euros.
If the rupee weakens against the euro, the same German expense requires more rupees.
For example, a university payment of €10,000 costs:
₹9 lakh at ₹90 per euro
₹10 lakh at ₹100 per euro
₹11 lakh at ₹110 per euro
This difference can create a funding gap even after loan sanction.
Students should:
Add an exchange-rate buffer
Ask which rate is used on the disbursement date
Check currency-conversion charges
Avoid planning with an unusually favorable rate
Retain emergency funds
Review whether the lender can increase the sanctioned amount
Loan Sanction vs Disbursement
Sanction and disbursement are different stages.
Loan Sanction
The lender approves a maximum amount subject to conditions.
The sanction letter may mention:
Approved limit
Interest rate
Collateral
Co-applicant
Margin
Moratorium
Repayment
Conditions before disbursement
Loan Disbursement
The lender releases money after required conditions are satisfied.
Disbursement may be made:
Directly to the university
To a blocked-account provider
To an insurance provider
As reimbursement of approved expenses
To the borrower for eligible documented costs
The lender may require a fresh invoice, enrollment confirmation, academic-progress report, visa, or borrower contribution before each installment.
Documents Required for an Education Loan
Student Documents
Completed loan application
Passport
PAN
Aadhaar or accepted identity document
Address proof
Admission letter
University fee structure
Course details
Academic certificates
Academic transcripts
Class 10 and Class 12 documents
Entrance-test or language-test scores
APS certificate where available or required
Curriculum vitae
Scholarship letter, if applicable
Statement of purpose where requested
Employment documents for working applicants
Passport-size photographs
Co-Applicant Documents
PAN
Aadhaar or identity proof
Address proof
Relationship proof
Salary slips
Bank statements
Income-tax returns
Form 16
Employment certificate
Business registration
Audited financial statements
GST documents where applicable
Existing loan statements
Asset and liability details
Collateral Documents
Property title documents
Sale deed
Approved plan
Tax receipts
Encumbrance certificate
Mutation records
Valuation documents
Legal-clearance documents
Fixed-deposit receipt or financial-security records
The lender can request additional documents based on the applicant’s profile.
How to Apply for an Education Loan for Germany
Step 1: Estimate the Complete Cost
Include tuition, living expenses, blocked account, travel, insurance, semester contribution, deposits, and emergency funds.
Step 2: Check University and Course Eligibility
Ask lenders whether the exact university and degree qualify for their overseas education product.
Step 3: Decide Between Secured and Unsecured Funding
Compare approval probability, rate, tenure, collateral risk, and total repayment.
Step 4: Evaluate the Co-Applicant
Check income stability, credit history, existing EMIs, and document availability.
Step 5: Collect Documents
Prepare academic, admission, financial, identity, and collateral files.
Step 6: Compare Multiple Lenders
Obtain written offers from more than one lender where possible.
Compare:
APR
Interest rate
Margin
Moratorium
Repayment tenure
Processing fee
Collateral
Covered expenses
Disbursement method
Prepayment terms
Penal charges
Step 7: Submit the Application
Apply through the lender’s official channel, branch, or authorized education-loan portal.
Step 8: Complete Credit and Collateral Checks
The lender evaluates the student, co-applicant, course, university, repayment potential, and security.
Step 9: Review the Sanction Letter
Verify every condition before accepting.
Step 10: Arrange the Blocked Account
Confirm whether the lender will transfer the required amount directly to the blocked-account provider.
Step 11: Complete Disbursement Conditions
Submit the visa, university invoice, margin contribution, insurance, or other documents requested.
Step 12: Track Every Payment
Maintain copies of transfer receipts, SWIFT details, university acknowledgments, and loan statements.
When Should Students Apply?
Students should begin loan preparation before the final visa stage.
| Time before enrollment | Recommended action |
|---|---|
| 9–12 months | Estimate costs and research lenders |
| 6–9 months | Organize co-applicant and collateral documents |
| 4–7 months | Secure admission and submit the loan application |
| 3–5 months | Complete valuation, legal checks, and sanction |
| 2–4 months | Arrange blocked account and initial disbursement |
| 1–3 months | Submit financial proof with the visa application |
| Before travel | Confirm university payment and access to emergency funds |
Students using property as collateral should allow additional time for legal and valuation procedures.
How Lenders Evaluate an Application
Lenders generally assess four major areas.
Student Profile
Academic consistency
Backlogs
Study gaps
Work experience
Language scores
Course progression
University and Course
Recognition
Reputation
Employment outcomes
Course duration
Subject
Tuition cost
Lender’s internal category
Co-Applicant Profile
Income
Credit score
Existing debt
Employment stability
Business performance
Repayment capacity
Collateral
Ownership
Legal title
Marketability
Valuation
Location
Existing mortgage
A strong university admit does not guarantee approval if the co-applicant has serious credit problems or the collateral is legally defective.
Reasons an Education Loan May Be Rejected
Common reasons include:
Unrecognized university
Ineligible course
Weak academic progression
Excessive backlogs
Unexplained study gap
Poor co-applicant credit score
Insufficient income
High existing debt
Incomplete documents
Unacceptable collateral
Defective property title
Requested amount exceeding lender policy
Uncertain employment potential
Inconsistent information
Previous loan default
Insufficient margin contribution
Students should ask whether the problem can be corrected through a smaller loan, stronger co-applicant, additional collateral, or different lender.
How to Improve Approval Chances
Apply after receiving a clear admission offer.
Choose a recognized, employment-oriented program.
Maintain accurate academic and financial records.
Explain study gaps and career changes.
Check the co-applicant’s credit report.
Reduce avoidable debt before applying.
Resolve property-document problems.
Include scholarships and personal savings.
Request a realistic amount.
Maintain an exchange-rate buffer.
Submit complete documents.
Compare secured and unsecured options.
Avoid multiple uncontrolled applications within a short period.
Education Loan Tax Benefit Under Section 80E
Eligible interest paid on a qualifying higher-education loan may be deductible under Section 80E of the Income Tax Act.
Important points include:
The deduction applies to eligible interest, not principal repayment.
The loan must satisfy the statutory conditions.
It should be taken from an eligible financial or approved institution.
Higher education can be for the individual or an eligible relative.
The official Income Tax portal currently describes the deduction as the total eligible interest paid.
Loan and interest details must be reported in the income-tax return.
Section 80E is generally relevant under the old tax regime; deductions available under the old regime may not be available under the default new regime.
The taxpayer should retain the interest certificate and repayment records.
Tax rules can change. The borrower should compare the old and new regimes and consult a qualified tax professional before claiming a deduction.
Prepayment and Foreclosure
Early repayment can reduce total interest, especially after the borrower starts earning.
Before prepaying, check:
Whether a charge applies
Whether the loan is floating or fixed
Minimum prepayment amount
Whether payment reduces EMI or tenure
How the payment should be labeled
Whether outstanding interest is cleared first
Whether collateral-release charges apply
Reducing tenure usually saves more interest than reducing EMI, provided the borrower can comfortably maintain the current installment.
Refinancing an Education Loan
A borrower may transfer the outstanding loan to another lender offering better terms.
Potential benefits include:
Lower interest rate
Lower EMI
Longer tenure
Better customer service
Release or replacement of collateral
Improved repayment structure
Potential costs include:
Processing fee
Legal charges
Valuation fee
Documentation expenses
Insurance changes
Foreclosure conditions
Longer total repayment period
A lower EMI does not always mean a cheaper loan. Compare the remaining total interest under both arrangements.
Education Loan vs Self-Funding
| Factor | Education loan | Self-funding |
|---|---|---|
| Family savings | Preserved to some extent | Reduced immediately |
| Interest cost | Payable | None |
| Financial discipline | Fixed repayment obligation | Greater flexibility |
| Collateral risk | Possible | None |
| Tax benefit | Possible on eligible interest | Not applicable |
| Emergency liquidity | Can be preserved | May become limited |
| Long-term burden | EMI after graduation | No education-loan EMI |
A balanced approach can combine savings, scholarship, and a smaller loan rather than financing every expense through debt.
Education Loan vs Scholarship
A scholarship does not normally require repayment, while an education loan does.
Students should apply for scholarships even after beginning the loan process. A scholarship can reduce:
Amount disbursed
Interest during study
Final principal
EMI
Repayment tenure
If a scholarship is received after sanction, inform the lender and request adjustment of future disbursements. Do not borrow more merely because a higher amount was approved.
Common Mistakes to Avoid
Calculating only tuition fees
Assuming tuition-free means expense-free
Believing a sanction letter automatically replaces the blocked account
Ignoring exchange-rate changes
Choosing a lender based only on the advertised rate
Not comparing APR
Ignoring processing, insurance, and legal charges
Signing incomplete forms
Accepting verbal promises
Assuming the moratorium is interest-free
Borrowing the maximum approved amount without need
Ignoring co-applicant liability
Pledging disputed property
Missing disbursement conditions
Depending on future part-time work
Choosing a long tenure without checking total interest
Paying unofficial agents
Not retaining payment records
Assuming a scholarship will definitely be awarded
Failing to maintain an emergency reserve
Education Loan Checklist
Before accepting a loan, confirm:
The university and course are eligible.
The total study budget is realistic.
The blocked-account requirement is included.
Tuition and semester contributions are correctly separated.
The exchange-rate buffer is adequate.
The sanctioned amount covers essential expenses.
Margin requirements are manageable.
Collateral documents are legally clear.
The co-applicant understands the liability.
The rate is fixed or floating as stated.
The benchmark and spread are disclosed.
The APR is available.
Moratorium interest is understood.
EMI has been calculated after capitalization.
Processing and legal charges are documented.
Penal charges are disclosed.
Prepayment rules are clear.
Disbursement to the blocked account is possible.
Visa timelines are considered.
All promises appear in writing.
Frequently Asked Questions
Can I get an education loan to study in Germany?
Yes. Indian banks and NBFCs offer overseas education loans for eligible German universities and courses.
How much loan can I get for Germany?
The amount depends on the university, course, total expenses, co-applicant, collateral, credit profile, and lender policy. Loans may range from smaller amounts for living expenses to substantial funding for tuition-charging programs.
Is collateral required?
Not always. Unsecured loans are available for selected universities and strong profiles. Larger amounts or weaker profiles may require collateral.
Can I get a loan for a tuition-free German university?
Yes. A loan may cover living expenses, blocked-account funding, semester contributions, travel, insurance, and other eligible costs even when tuition is zero.
Does an education loan replace the blocked account?
No. Students should not assume that a loan sanction letter alone replaces the blocked account. The loan can be used to transfer the required funds into an approved blocked account.
What is the current blocked-account amount?
Current German Missions in India guidance lists €11,904 for the first year, with a monthly withdrawal limit of €992. The figure can change and should be confirmed before transfer.
Can the bank transfer money directly to a blocked account?
Many overseas education-loan products allow eligible living-cost disbursement to a blocked-account provider. Students should confirm the process before accepting the sanction.
Can I get a loan without admission?
Most lenders require an admission or conditional admission letter before final sanction or disbursement. Some may provide provisional assessment earlier.
Is a co-applicant compulsory?
A co-applicant is commonly required. The accepted relationship and income conditions depend on the lender.
Are living expenses covered?
Yes, many overseas education loans cover eligible living expenses. The lender may apply limits or request proof based on the university or visa estimate.
Does the loan cover APS and visa expenses?
Some lenders include reasonable documentation and visa-related costs, while others exclude or limit them. Written confirmation is necessary.
Is the moratorium interest-free?
Usually not. Interest commonly accumulates during the course and moratorium unless a specific subsidy or lender scheme states otherwise.
Can I repay interest while studying?
Yes, if the lender permits it. Paying interest during study can reduce capitalization, EMI, and total repayment.
What interest rate applies?
Rates vary by lender, loan type, benchmark, university, collateral, and applicant profile. Students should compare the current APR and not depend on old rate lists.
What is margin money?
Margin money is the portion of the education cost the student or family must pay from their own funds.
Can I claim an income-tax deduction?
Eligible interest may qualify under Section 80E under applicable conditions, generally when using the old tax regime. Tax advice should be obtained for the borrower’s specific situation.
Can I combine a scholarship and education loan?
Yes, subject to the scholarship and lender conditions. The scholarship should be disclosed, and unnecessary loan disbursement should be reduced.
Can I prepay the education loan?
Yes, subject to the loan agreement and applicable rules. Borrowers should check charges and whether prepayment reduces tenure or EMI.
What happens if I do not get a job immediately?
The loan remains legally repayable according to the agreement. Students should maintain emergency funds and contact the lender early if repayment difficulty is expected.
Is a public-sector bank always cheaper than an NBFC?
Not in every case, but public-sector banks often provide competitive secured rates. NBFCs may offer faster or more flexible approval at a higher overall cost.
Should I take the maximum amount sanctioned?
No. Interest is charged on the disbursed amount, but unnecessary borrowing still increases future debt. Draw only what is genuinely needed.
Final Thoughts
An education loan can make studying in Germany possible without exhausting family savings, but it should be treated as a long-term financial commitment rather than easy funding.
Students should calculate the complete cost of attendance, understand that tuition-free study still requires substantial living funds, and arrange the German blocked account correctly. They should compare secured and unsecured offers using APR, moratorium interest, total repayment, collateral risk, and foreign-exchange exposure.
The best loan is not necessarily the one with the fastest approval, largest sanction, or lowest advertised rate. It is the loan that provides sufficient funding, clear conditions, affordable repayment, and reliable disbursement for the university and visa timeline.
Interest rates, visa requirements, blocked-account amounts, tax rules, and lender policies can change. Students should confirm current conditions with the lender, German Missions in India, Reserve Bank of India, Income Tax Department, and selected German university before making a financial commitment.